
With a Charitable Gift Annuity (CGA), you can make a gift and receive a guaranteed stream of fixed income payments for life.
OPTION 1—an immediate CGA
You may find that one or more CGAs can be a rewarding part of your retirement plan. Consider the following:
- You can implement a CGA with a modest contribution of cash, stocks, or mutual funds.
- You can elect a payment arrangement that is convenient for you (typically, annual or quarterly payments).
- You qualify for an immediate income tax charitable deduction for the gift part of the transaction (not the annuity part of the transaction), subject to limitations.
- If you fund the CGA with appreciated assets, you may be able to spread out capital gains tax liability.
- Part of each annuity payment may be income tax free.
- You can count on and plan for a lifetime income stream for yourself and/or a loved one (two people max).
The payment amount is based on:
- The amount of the gift (higher gift amount = higher payment amount)
- The age(s) of whoever will be receiving the payments (older annuitant = higher payment amount)
- When payments will begin (longer deferral = higher payment amount)
- The current rates for CGAs
Sample one-life Gift Annuity rates, effective since January 2024.
Age | 70 | 75 | 80 | 85 | 90 |
Rate | 6.3% | 7.0% | 8.1% | 9.1% | 10.1% |
Rates are subject to change. Contact us to verify the rate for your age.
OPTION 2—a deferred CGA
This is an easy way to make a gift now but start receiving payments at a specified future date. You can time payments to retirement while locking in a higher income payment when compared with an otherwise similar immediate CGA.
- You select a payment start date at least one year in the future.
- Your gift still qualifies for an immediate income tax deduction (subject to limitations).
OPTION 3—a flexible deferred CGA
This is simply a deferred CGA with an unspecified future start date. It allows you to postpone the decision on when you want to begin receiving payments within a predetermined time frame.
- You will receive a smaller immediate deduction based on the earliest possible start date.
- Your annuity rate increases with each year you continue to defer payments.
- Payments will begin automatically at the end of the time frame if you have not yet asked for them to begin.
This added flexibility is particularly useful for those who:
- Want to begin payments at retirement but have not yet chosen a retirement date
- Face a future expense without clear timing (such as the anticipated need to pay for a relative’s nursing home care)
- Want to maximize their annuity rate (and therefore payment amount) by waiting but are concerned they may need to begin receiving payments earlier
Evaluate the fit.
CGAs may be a particularly good option to consider if you:
- Want to ensure that Turning Point is funded beyond your lifetime
- Are retired or near retirement
- Want to establish a source of fixed income payments to supplement other income streams in retirement
- Want to establish a source of fixed income for a loved one
- Could use a current income tax charitable deduction
- Would like to get rid of appreciated assets but do not want to pay the associated capital gains tax
- Are an IRA owner age 70½ or older who wishes to make a one-time distribution to create a CGA
- Are comfortable funding the CGA with a minimum of $25,000
See how it works.
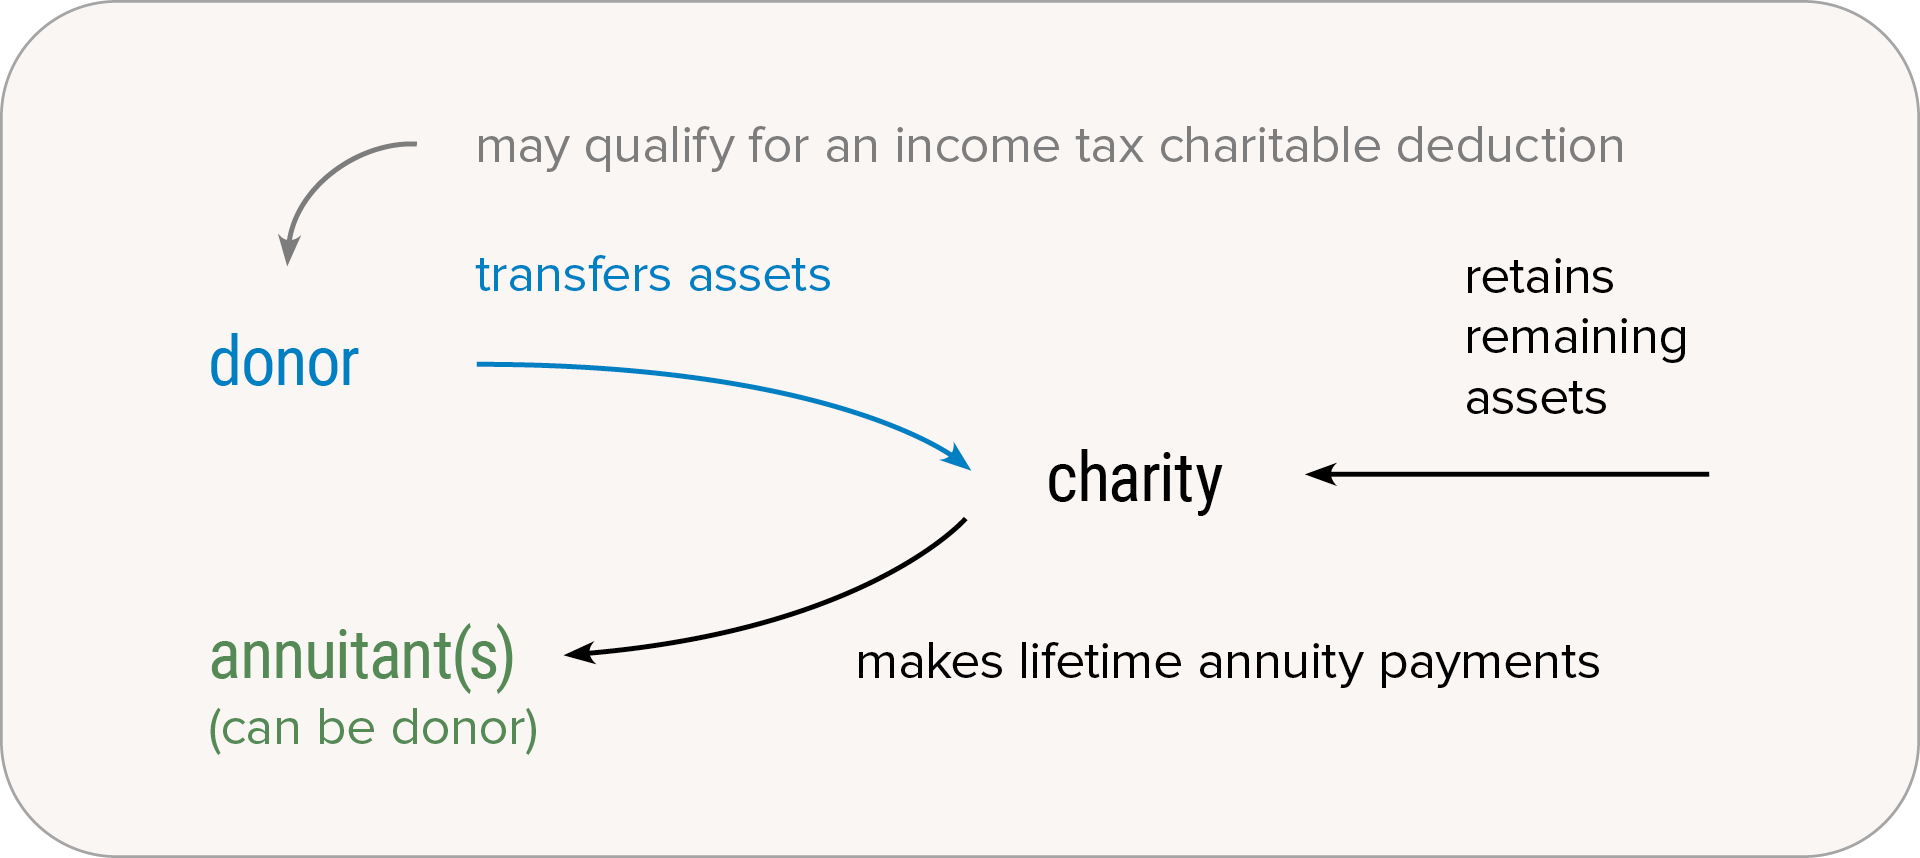
Sarah makes an irrevocable gift of appreciated stock using a Charitable Gift Annuity. In return, Sarah receives lifetime annuity payments based on her age, the Gift Annuity rate, and the gift amount. Sarah enjoys favorable taxation—part of each payment is tax-free return of principal, part is long-term capital gain, and the remainder is taxed as ordinary income.
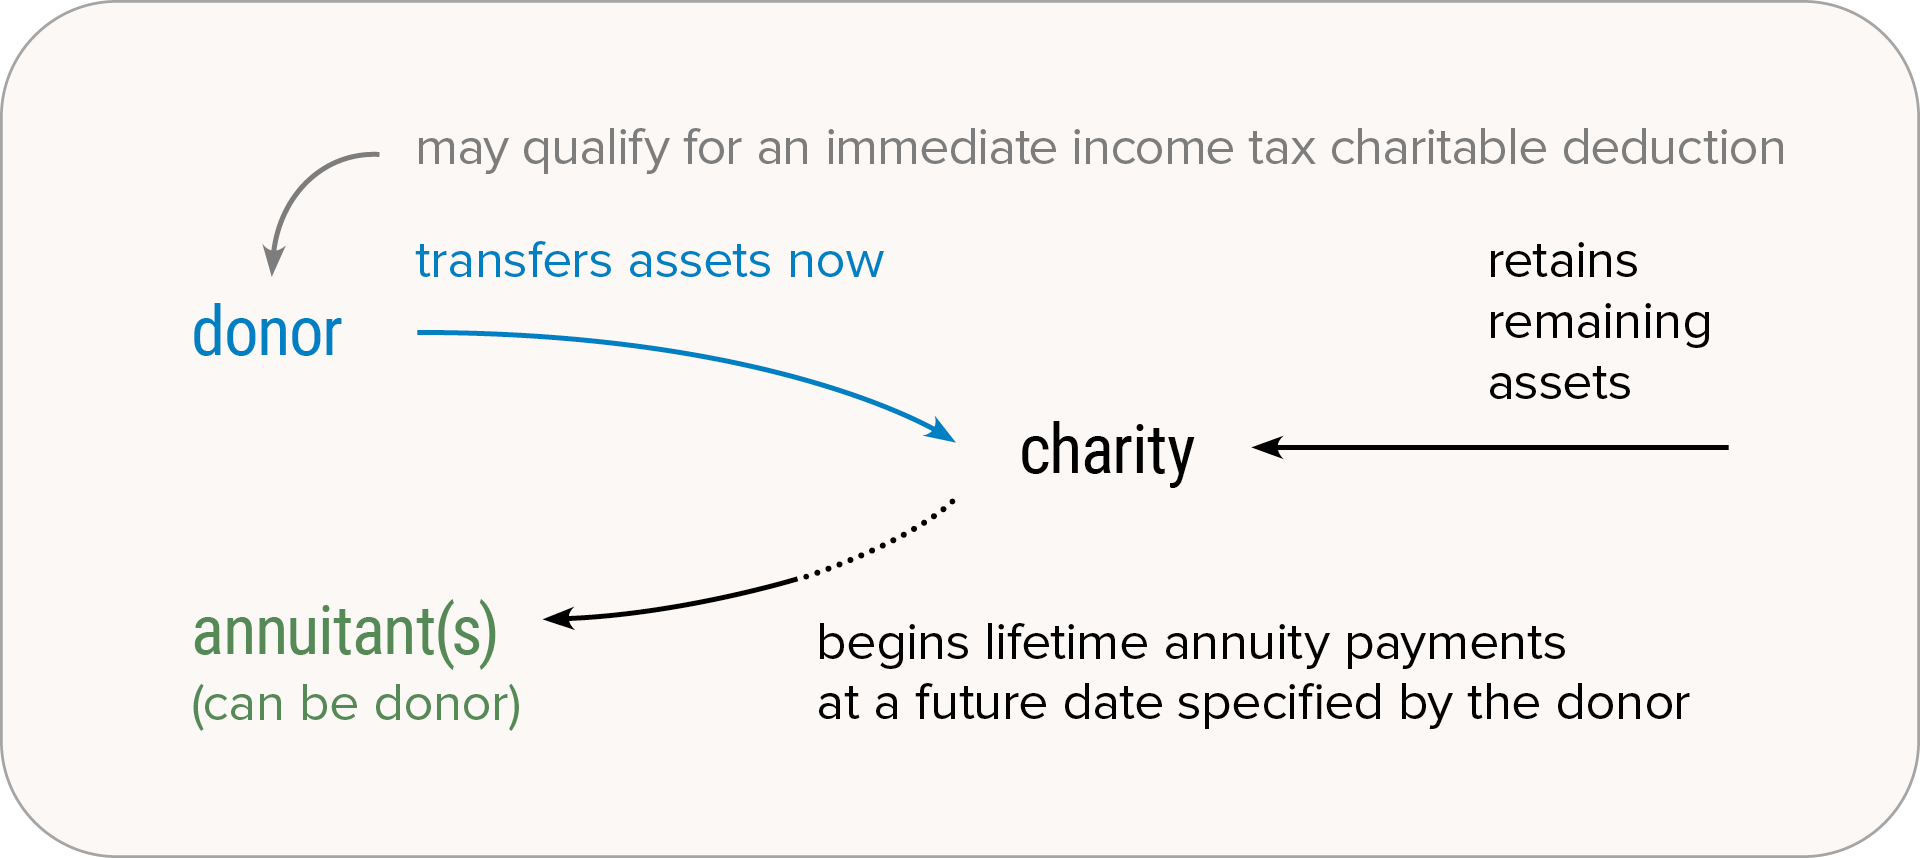
Aaron (age 58) does not need additional income right now, but he would like to reduce his current income tax liability and supplement his future retirement income. He selects a Deferred Charitable Gift Annuity. He makes an irrevocable gift, and in return, receives lifetime annuity payments beginning in 10 years. By delaying the start of payments, he increases his annuity income and the gift qualifies for a larger tax deduction.
A one-time funding option
Note that an IRA owner age 70½ or older can choose to fund a new CGA by making a one-time, tax-free distribution from the IRA of up to $55,000 (in 2026). (Spouses may combine distributions from their own IRAs into a joint-life CGA.) This distribution does not create an income tax charitable deduction, but it does count toward the donor’s required minimum distribution if one is due. A CGA created this way has slightly different rules from regular CGAs.
Consider your timing.
If you want to qualify for a charitable deduction this year, you should have the CGA application and contribution to us by December 13.
We can help.
We can provide you with one or more complimentary illustrations to help you estimate your deduction, your income payment amount, and your tax impact.
The Ministry's information is:
Legal name: Turning Point for God
Tax identification number: 33-0095805
10007 Riverford Rd.
Lakeside, CA 92040
(619) 258-3600
Contact Turning Point Ministries Foundation
Toll-Free Phone: 1-833-HIS-WORK (447-9675)
Email: PlannedGiving@DavidJeremiah.org