
With a gift from your IRA, you have a few options for making a powerful impact.
OPTION 1—an outright gift
This is a Qualified Charitable Distribution (QCD) you can make every year if you wish. You may find it appealing if you would like to make an immediate gift that counts toward your required minimum distribution (RMD). It works like this:
- If you are an IRA owner age 70½ or older, you can direct a QCD to be transferred from your IRA directly to Turning Point.
- The gift does not qualify for an income tax deduction, but any amount up to the annual aggregate limit ($111,000 in 2026) is tax free.
- The gift counts toward your RMD if one is due (generally beginning at age 73).
- Your gift has an immediate impact on our ministry, and you can make this gift every year if you choose.
OPTION 2—a life income gift
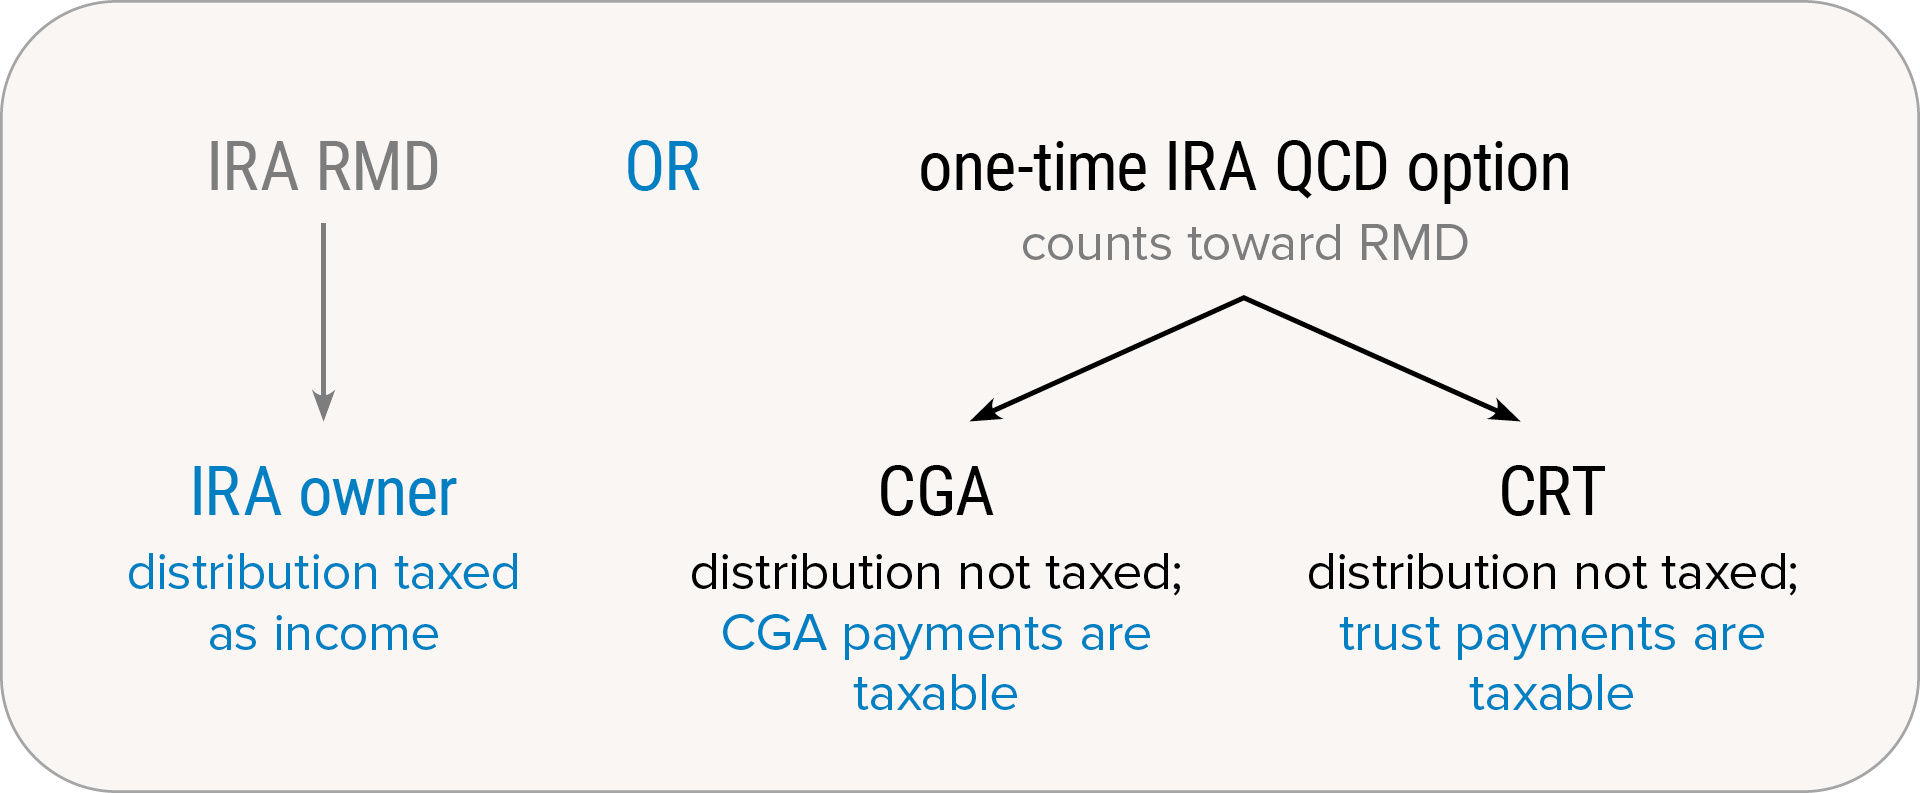
This one-time Qualified Charitable Distribution (QCD) lets you make a gift that counts toward your RMD and also creates a new income stream for retirement. It works like this:
- If you are an IRA owner age 70½ or older, you can direct a QCD to be transferred from your IRA to create a new Charitable Gift Annuity (CGA) or Charitable Remainder Trust (CRT).
- The gift does not qualify for an income tax deduction, but any amount up to the limit ($55,000 in 2026) is tax free.
- The gift counts toward your RMD if one is due (generally beginning at age 73).
- Spouses may contribute up to $55,000 each from their own IRAs into a single CRT or a joint-life CGA.
- Income payments may only go to the IRA owner and the owner’s spouse and are taxed at ordinary income tax rates.
- This is not an annual gift—you may only use this option once.
To learn more about these options, click here to read about Charitable Gift Annuities or Charitable Remainder Trusts. Keep in mind that some of the rules and requirements differ if you fund the CGA or CRT from your IRA.
OPTION 3—a charitable beneficiary designation
You may prefer this option if you want to give a future gift that costs you nothing today. It works like this:
- At any age, ask your IRA custodian for a Change of Beneficiary form.
- You can name Turning Point as the sole beneficiary or a percentage beneficiary.
- You pay nothing now and retain the right to change your gift if your needs and goals change.
- After you pass away, Turning Point will receive the designated assets from your IRA.

Why leave retirement assets to charity?
Retirement account assets left to heirs are highly taxed—once in your estate and again as income to the beneficiaries. Since Turning Point is a church and tax-exempt, it can receive retirement funds without triggering the heavy income taxes that usually hit individual heirs. By using IRA assets to make charitable gifts to ministries like Turning Point and leaving other assets (like stocks, bonds, mutual funds) to family members, you minimize the income tax burden on your heirs, leave more to your intended beneficiaries, and maximize your charitable goals.
Evaluate the fit.
A gift from your IRA may be a particularly good option to consider if you:
- Want to ensure more resources go toward eternal Kingdom impact
- Are an IRA owner age 70½ or older
- Want to avoid paying tax on an RMD you do not need
- Want to establish a source of fixed income payments to supplement other income streams in retirement
See how it works.
Miriam, age 75, is required to take a taxable IRA distribution of $15,000 this year. Miriam wants to support our ministry and decides to make a Qualified Charitable Distribution, transferring $15,000 directly from the IRA to us. The transfer counts toward Miriam’s RMD, satisfying the distribution requirement, but no tax is due on the distribution. The full amount of the transfer supports Turning Point—nothing is lost to taxes!

This year, Sam, age 75, makes a one-time, tax-free QCD of $55,000 to fund a CGA with Turning Point—an easy way to support our work helping others grow in their faith. Sam will receive an annual payment of $3,850 for life, and these payments are taxable each year. If Sam had decided to personally receive the $55,000 distribution this year instead of using it for a QCD, the full amount would have been currently taxable.
Consider your timing.
An outright gift from your IRA can usually be completed if you begin the process in early December. A QCD from a “checkbook IRA” may need additional time to ensure that the check clears by December 31 (in other words, if you want the distribution to count this year for tax reporting purposes, make sure we have enough time to both receive and cash the check). The one-time, life income option may require even more time to set up the CGA or CRT. A beneficiary designation is quick and easy to make at any time.
We can help.
We can provide you with more information about any of these options for using your IRA assets to make a gift. You will work directly with your IRA custodian to accomplish these gifts. Please request that your name and address as the donor be included with the check, or contact us in advance to provide this information so we may provide substantiation for your Qualified Charitable Distributions. If you make a beneficiary designation, we would like the opportunity to thank you.
Where to mail IRA gifts:
Turning Point for God
P.O. Box 3838
San Diego, CA 92163-1838
EIN # 33-0095805
The Ministry's information is:
Legal name: Turning Point for God
Tax identification number: 33-0095805
10007 Riverford Rd.
Lakeside, CA 92040
(619) 258-3600
Contact Turning Point Ministries Foundation
Toll-Free Phone: 1-833-HIS-WORK (447-9675)
Email: PlannedGiving@DavidJeremiah.org